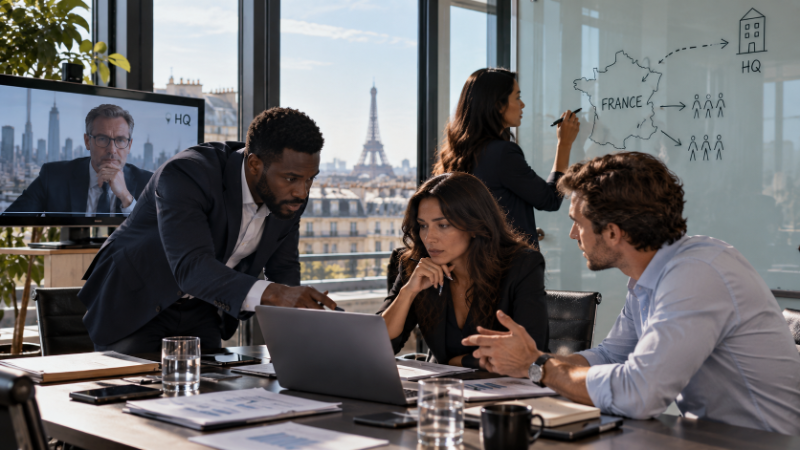
A foreign company has been selling to French customers for around ten years. It has never incorporated a French subsidiary. It has a small team in Paris, hosted by a French sister company remunerated on a cost plus basis, whose intra-group agreement expressly confines it to prospecting and support. Customer contracts are signed at head office. When the French tax authorities ask the sister company for the names of its commercial contacts and for its correspondence with French customers, nobody is concerned: the agreement is unambiguous, and the signature is foreign. The assessment notice arrives six months later, at the head office address. It finds a permanent establishment in France and covers ten financial years.
A permanent establishment is not a structure that anyone sets up. It is a characterisation that the law draws from conduct, which means it can be established years after the fact, over periods the business believed were closed. The real question is not how to operate in France without creating a permanent establishment. It is whether the arrangement already running has created one that nobody decided upon.
No. The Conseil d’État, France’s supreme administrative court, holds that a foreign company has a permanent establishment in France where staff based in France in fact decide to conclude with customers, even though formal signature takes place abroad. The characterisation follows the real working of the commercial relationship, not the allocation of roles recorded in the intra-group agreement.
This is the most dangerous form of permanent establishment, because it requires no premises, no signage and no registration. A person who acts in France on behalf of the foreign enterprise without genuine independence from it is enough. The court looks at who negotiates price, who settles commercial terms, who handles the customer’s objections, and what head office actually does when a file reaches it. Where the foreign signature is no more than formal approval of what was decided in France, it protects nothing.
The applicable double tax treaty does not necessarily close the point. Since 2019, a collective treaty arising from the OECD’s work has rewritten a large number of France’s treaties without any of them being renegotiated. It now expressly captures a person who habitually plays the principal role leading to the conclusion of contracts that are routinely concluded without material modification by the enterprise, and it denies independent agent status to a person acting exclusively or almost exclusively for closely related enterprises. This calls for verification treaty by treaty: the instrument amends a bilateral text only where both States have notified it.
No, and this is a constant source of unpleasant surprise. They are autonomous concepts: the VAT notion derives from European Union law and turns on having the human and technical resources enabling services to be supplied independently. An arrangement may be a permanent establishment for one and not for the other.
For VAT purposes the consequence is immediate. The establishment becomes liable for the tax on services supplied from France to French customers, and the reverse charge mechanism, under which the French customer accounts for the tax in place of the foreign supplier, is displaced. The fact that customers have themselves paid the VAT has been held to be irrelevant: the principles of neutrality and effectiveness do not operate to change who is liable. The business finds itself paying tax already remitted to the French Treasury by its own customers, and the double payment can only be addressed separately, through claims that depend on those customers’ cooperation.
No, and the Conseil d’État closed that door in spring 2025. A company that has neither filed French returns nor made its activity known to the French business formalities portal is treated as carrying on a concealed activity, unless it establishes that it made an error justifying its failure to meet any filing obligation whatsoever. Where it argues that it declared everything elsewhere, that error is assessed having regard in particular to the level of taxation in the other State and to the arrangements for exchange of information between the two tax administrations.
The rule repays slow reading, because it inverts the intuition. The lower the tax burden in the home State, the harder good faith is to establish. A group entirely compliant at home, which has concealed nothing, may therefore face the concealed activity characterisation on the sole ground that its local rate is appreciably below the French rate. The characterisation is not a matter of vocabulary: it extends the assessment period from three years to ten and triggers the 80 per cent surcharge. The argument that the case law adapted the permanent establishment concept to the digital economy only after the years in dispute has been expressly rejected.
A foreign company that has filed no returns in France is assessed ex officio. The French tax authorities themselves reconstruct the profit attributable to the permanent establishment, in practice from banking receipts and a cost ratio fixed by no statutory provision, and the burden of proof lies with the business.
The trap then closes on itself. To challenge that ratio to any effect, the company must produce evidence specific to the activity of its permanent establishment, meaning dedicated accounts, which is precisely what their absence justified the reconstruction. Comparison with companies said to be comparable has already been held insufficient. For companies established outside the European Union and the European Economic Area, there is the further branch tax under article 115 quinquies of the Code général des impôts, the French tax code, which deems profits made in France, after corporation tax, to be distributed to non-resident shareholders, together with late payment interest of 0.20 per cent per month, due in all cases, including in complete good faith.
The total goes well beyond the tax avoided. Penalties are not deductible, and so are paid out of after-tax money. Double taxation does not resolve itself: the business has already paid on the same profits in its home State, and relief requires a mutual agreement procedure between the two administrations, slow, subject to a filing deadline, and materially complicated by a bad faith penalty.
Yes, for as long as the French tax authorities have taken no step. A move made before any formal notice, any audit notification and any request for information removes the concealed activity characterisation, brings the assessment period back to three years, avoids ex officio assessment and allows the company to establish its own figures rather than suffer a reconstruction. The window closes with the first letter received, and a return filed in the wrong order amounts to an admission of the characterisation, with no way back.
The gap between the two scenarios is not marginal: on an activity of any size, it changes whether the business remains solvent. What makes the decision difficult is therefore not whether it is worthwhile, which is a matter of arithmetic, but its sequencing. Regularising means accepting a characterisation for the past, with its filing, accounting and sometimes contractual consequences, and dealing separately with the form in which the activity continues. Two instruments come up regularly, and both call for a careful hand: the ruling by which a company resident in a treaty State asks for confirmation that it has no permanent establishment in France, which is also a signal sent to the French tax authorities and is not launched without thought; and in-audit regularisation, which covers only returns filed within time and is therefore of no use to a company that has never filed anything. Confusion on this second point is common and expensive.
A permanent establishment file is not lost on the day of the audit. It is lost on the day a commercial arrangement settles in for the long term without anyone checking what it produced as a matter of law, and it then turns almost entirely on two points: the concealed activity characterisation, which governs the number of years and the rate of the surcharge, and whether the approach is treated as voluntary, which governs whether the business or the French tax authorities hold the pen on the figures. Both are settled before the first letter arrives.
In the inbound files I see at Lobe Law, the concealed activity characterisation is almost always the main issue, ahead of the amount of tax itself.
The group in our scenario had ten years of opportunities to have its French arrangement looked at. What cost it most was not having a team in Paris. It was believing that the agreement answered the question.
Lobe Law, a tax law practice in Paris, reviews the real exposure of your French arrangement and settles the sequence of any regularisation before contact with the French tax authorities. Book a consultation.